Partnership targets Level 4 robotaxis on Lucid’s Midsize platform as Bolt scales its long-term AV network
Lucid and Bolt said on September 17, 2026 that they plan to deploy at least 25,000 autonomous Lucid EVs across Europe, with Bolt aiming to use the deal as part of a broader target of 100,000 autonomous vehicles on its platform by 2035.
The vehicles are slated to be built on Lucid’s upcoming Midsize platform and designed for SAE Level 4 autonomy, while Bolt said its Bolt Autonomous Driving Solutions unit intends to own and operate the fleet itself.
The agreement gives Lucid a second major robotaxi vehicle supply deal in just over a year, after Uber committed in July 2025 to deploy 20,000 Lucid Gravity robotaxis in the US alongside a $300 million investment, according to the companies.
The catch is that Lucid’s Midsize platform has not launched and was delayed in the company’s August 4 Q2 “operational reset,” a period that also included an 18% workforce cut, the withdrawal of 2026 production guidance, and second-quarter deliveries of 3,953 vehicles.
Lucid just signed up to supply 25,000 autonomous EVs in Europe while the vehicle platform behind the deal still has not shipped. That contrast is the real story, and it matters because Lucid is stacking big robotaxi commitments faster than it is building cars.
Lucid and Bolt to deploy 25,000 autonomous EVs across Europe is a large headline number, but the deal is really a bet on future manufacturing and future autonomy at the same time. Bolt brings operating scale and a consumer network across Europe, while Lucid is again positioning itself primarily as the hardware provider, not the company supplying the self-driving stack.
Bolt said it will put at least 25,000 self-driving Lucid vehicles on its ride-hailing network in Europe. The companies said the cars will be built on Lucid’s upcoming Midsize platform, engineered for SAE Level 4 autonomy, and developed from the product stage as an “ADS-ready” vehicle using NVIDIA Hyperion, which the companies described as a production-ready reference architecture combining compute and a standard sensor suite.
That sounds substantial, and it is. Bolt is not a speculative startup. The company says it has more than 200 million customers, 4.5 million drivers and couriers, and operations in over 50 countries and 850 cities. For any autonomous vehicle program, that operating footprint is one of the more valuable assets on the table, especially in Europe, where regulations, city policies, and street geometry vary more than in a single-country rollout in the US.
Still, the press release math is doing some heavy lifting here. Lucid is promising vehicles for a robotaxi push on a platform it delayed just six weeks ago. On August 4, during its Q2 “operational reset,” the company pushed back the Midsize program, according to the company. That same reset included an 18% workforce reduction, about 1,500 jobs, the appointment of Silvio Napoli as permanent CEO on June 1, and the withdrawal of Lucid’s 2026 production guidance.
Lucid said shared autonomous mobility is an opportunity to extend its technology beyond consumer vehicles. Bolt said autonomous driving in Europe requires data, software, vehicles, and operations to work as one system built for European roads and regulation.
That wording matters. It points to the central unresolved issue in this deal: who actually supplies the autonomy. NVIDIA Hyperion is not itself a self-driving system. It is the computing and sensor architecture. The announcement also said the partners plan to work with autonomous-driving technology partners, which leaves the most difficult piece of the product, the software stack that can reliably operate at Level 4, still open.
25,000 vehicles
That is the minimum size of the planned Lucid and Bolt autonomous EV deployment across Europe, according to the companies.
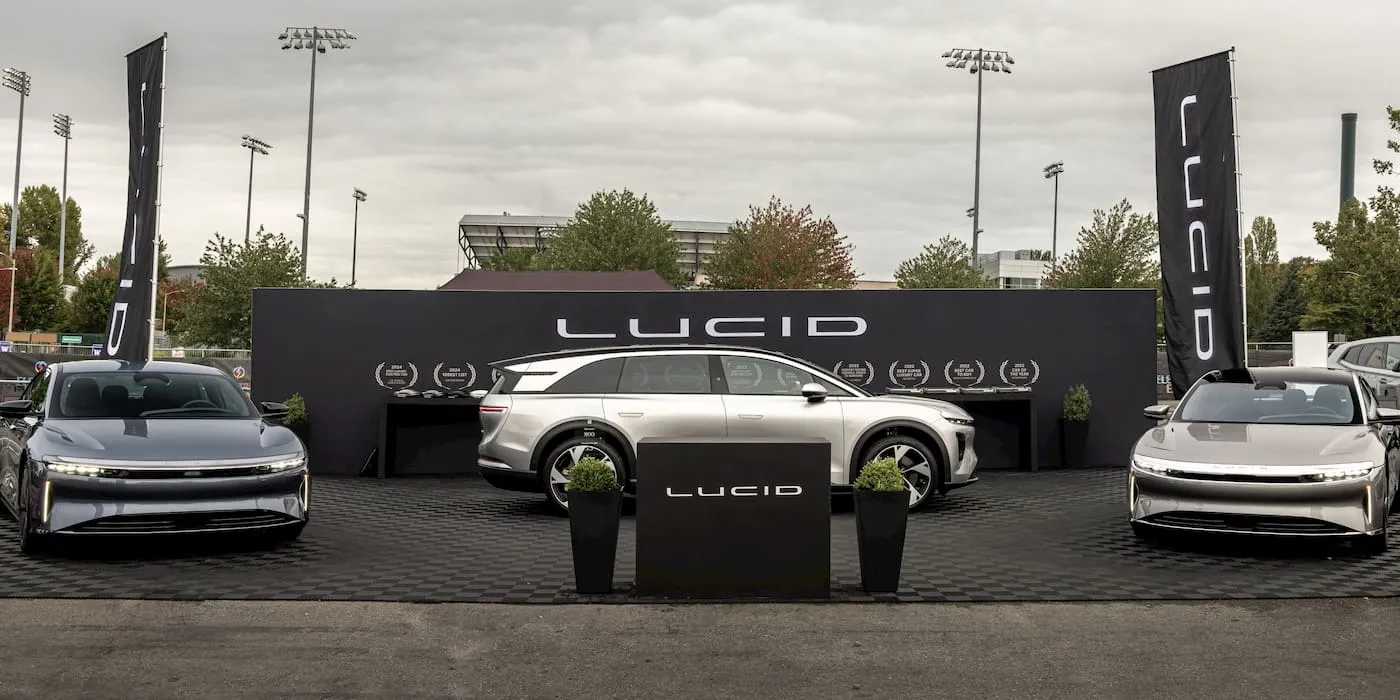
For US readers, there is a familiar pattern here. Lucid is assembling a role that looks a lot like a premium EV chassis and systems supplier to fleet operators and autonomy companies. In July 2025, Uber committed to deploy 20,000 Lucid Gravity robotaxis in the US using Nuro’s Driver system, alongside a $300 million investment, according to the companies. Uber later built its stake in Lucid to roughly 11.5%, according to an April 21, 2026 report cited in the source material.
Add the Bolt agreement and Lucid now has announced commitments totaling 45,000 autonomous vehicles across two continents. That is a striking number for a company this size. It delivered just 3,953 vehicles in the second quarter, according to the company. Even allowing for long rollout windows, the gap between declared fleet demand and current output is hard to ignore.
There is another reason this matters beyond Lucid’s own story. The robotaxi market is splitting into layers. Waymo has pushed a vertically integrated model. Uber has moved in a different direction, lining up partners and trying to avoid dependence on a single AV provider. Lucid’s recent deals suggest there may be a third lane for automakers: supply premium, software-ready vehicles to fleet operators that want control over demand, dispatch, and city operations but not necessarily the full burden of vehicle engineering.
Europe also makes this more interesting than a standard fleet supply announcement. Bolt said its dedicated Bolt Autonomous Driving Solutions unit will define vehicle, software, and safety requirements, build fleet infrastructure and city partnerships, and own and operate the fleet. In other words, Bolt is not just buying cars. It wants to be the operator. That is closer to the logic other AV companies have followed in practice, where the economics live or die on utilization, maintenance, insurance, permitting, and service density, not just vehicle bill of materials.
The challenge is that Europe has historically been a tougher proving ground for scaled autonomy than many US markets. Dense cities, older roads, fragmented regulation, and country-by-country operating rules make it harder to standardize deployments. Bolt’s comment about roads and regulation was not filler. It was the point. If Bolt can make this work in multiple European markets, that would say as much about its operating machine as Lucid’s vehicles.
The background
Lucid has spent much of the past year in an awkward position. The company is still trying to prove it can scale its consumer EV business, even as it signs very large autonomous-fleet deals that imply a second life as a platform supplier. Investors may like the optionality. Operators may like the idea of a high-end EV designed from the outset to be “ADS-ready.” But announcements do not erase execution risk.
The Midsize platform is the biggest immediate issue. This Bolt deal depends on it, and Lucid has already delayed it. That means the company is asking the market to underwrite a future product, a future fleet buildout, and a future autonomy partner all at once. In the robotaxi business, any one of those can slip. Here, all three are linked.
Bolt, for its part, has the cleaner strategic logic. The company says the 25,000-vehicle deployment is a step toward putting 100,000 autonomous vehicles on its platform by 2035. With 200 million customers, 4.5 million drivers and couriers, and a presence in 850 cities, Bolt has a distribution and operations base that many AV startups spent years trying to approximate. If autonomy becomes a service business before it becomes a pure technology business, that could matter a lot.
What's next
The next concrete trigger is not a robotaxi launch date, because neither company provided one. It is Lucid’s progress on the delayed Midsize program and whether the companies name the autonomous-driving software partner that will make Level 4 possible. Until those two pieces are clearer, Lucid and Bolt to deploy 25,000 remains a serious commercial signal, but not yet an operational reality.
Frequently asked questions
What does Lucid and Bolt to deploy 25,000 autonomous EVs across Europe mean?
It means Lucid and Bolt plan to roll out at least 25,000 self-driving electric vehicles in European markets. The vehicles are expected to use Lucid’s upcoming Midsize platform and be built for SAE Level 4 autonomy.
Where will the Lucid and Bolt autonomous EV fleet be deployed?
The companies said the deployment is planned across Europe, though they have not yet listed every launch market. The move positions Europe as a major growth region for Bolt’s autonomous ride-hailing ambitions.
What kind of autonomous technology will these Lucid vehicles use?
The planned vehicles are designed for SAE Level 4 autonomy, which means they can handle driving tasks on their own in specific conditions and areas. Bolt said the program will involve its Bolt Autonomous Driving Solutions technology stack.
Why is the Lucid and Bolt 25,000-vehicle deal important?
The agreement is significant because it combines Lucid’s EV platform with Bolt’s self-driving strategy at a large scale. Bolt also tied the deal to its broader goal of reaching 100,000 autonomous vehicles on its platform by 2035.
Will these 25,000 autonomous Lucid EVs be private cars or robotaxis?
Based on the companies’ statements, the vehicles are aimed at autonomous mobility services rather than traditional consumer ownership. That strongly suggests use in ride-hailing or robotaxi-style operations across selected European cities.
When will Lucid and Bolt start deploying autonomous EVs in Europe?
The announcement was made on September 17, 2026, but the companies did not provide a full rollout schedule in the preview details. More specifics on production timing, launch cities, and fleet operations will likely come closer to deployment.